Germany’s regional data centre opportunity: geographical selection and platform strategy will determine investor returns
14 September 2026 | Transaction
Mirko René Gramatke | Daniel Ponte Fernández | Mark Maczat | Marcel Philippe Quasigroch
Article | PDF | Data centres
“Germany’s data centre growth story is moving beyond Frankfurt, creating significant opportunities across regional markets.”

Germany’s data centre market is becoming increasingly decentralised. While Frankfurt remains the country’s leading hub, demand for enterprise co-location is spreading across regional markets including Berlin, Munich, Cologne/Düsseldorf, Hamburg, Stuttgart and Nuremberg. Analysys Mason forecasts demand to grow by ~8–9% annually in the coming years.
However, investment opportunities vary significantly by region. Local industry mix, existing capacity and development pipelines will determine whether some markets are likely to face supply shortages and stronger pricing power, while others may experience periods of excess capacity.
For investors, success will depend on understanding regional supply and demand dynamics, aligning expansion plans with local absorption rates and using buy-and-build strategies selectively to create scalable regional platforms.
Enterprise co-location growth is shifting beyond Frankfurt
Frankfurt remains Germany’s leading data centre market, underpinned by the largest digital infrastructure ecosystem in Europe. Driven by DE-CIX and a long-established concentration of carriers, data centre operators, hyperscalers, cloud providers and enterprise customers, the market benefits from strong network effects that continue to reinforce its position as the country’s primary data centre hub. Demand for new capacity is expected to remain robust, with upcoming developments anticipated to achieve high levels of pre-commitment.
Recent years have seen strong investor interest in hyperscale-focused platforms, a rapidly growing segment fuelled by substantial investment in AI infrastructure and large language models by technology giants such as Microsoft, Google, AWS and Meta, which increasingly rely on third-party data centre providers to support their expansion. As major data centre platforms increasingly prioritise hyperscale clients, significant opportunities emerge for other providers to capture demand within the enterprise co-location market.
Enterprise co-location remains a structurally attractive market in Germany, with demand expected to increase by ~8–9% per annum between 2025 and 2030. Growth is driven by the ongoing digital transformation of German Mittelstand (medium-sized enterprises), alongside rising demand for regional private cloud and co-location capacity. Given the often regional footprint of German small and medium-sized enterprises (SMEs), co-location requirements are inherently local, reflecting the need for proximity to customers. As a result, demand is most effectively served at the metropolitan level.
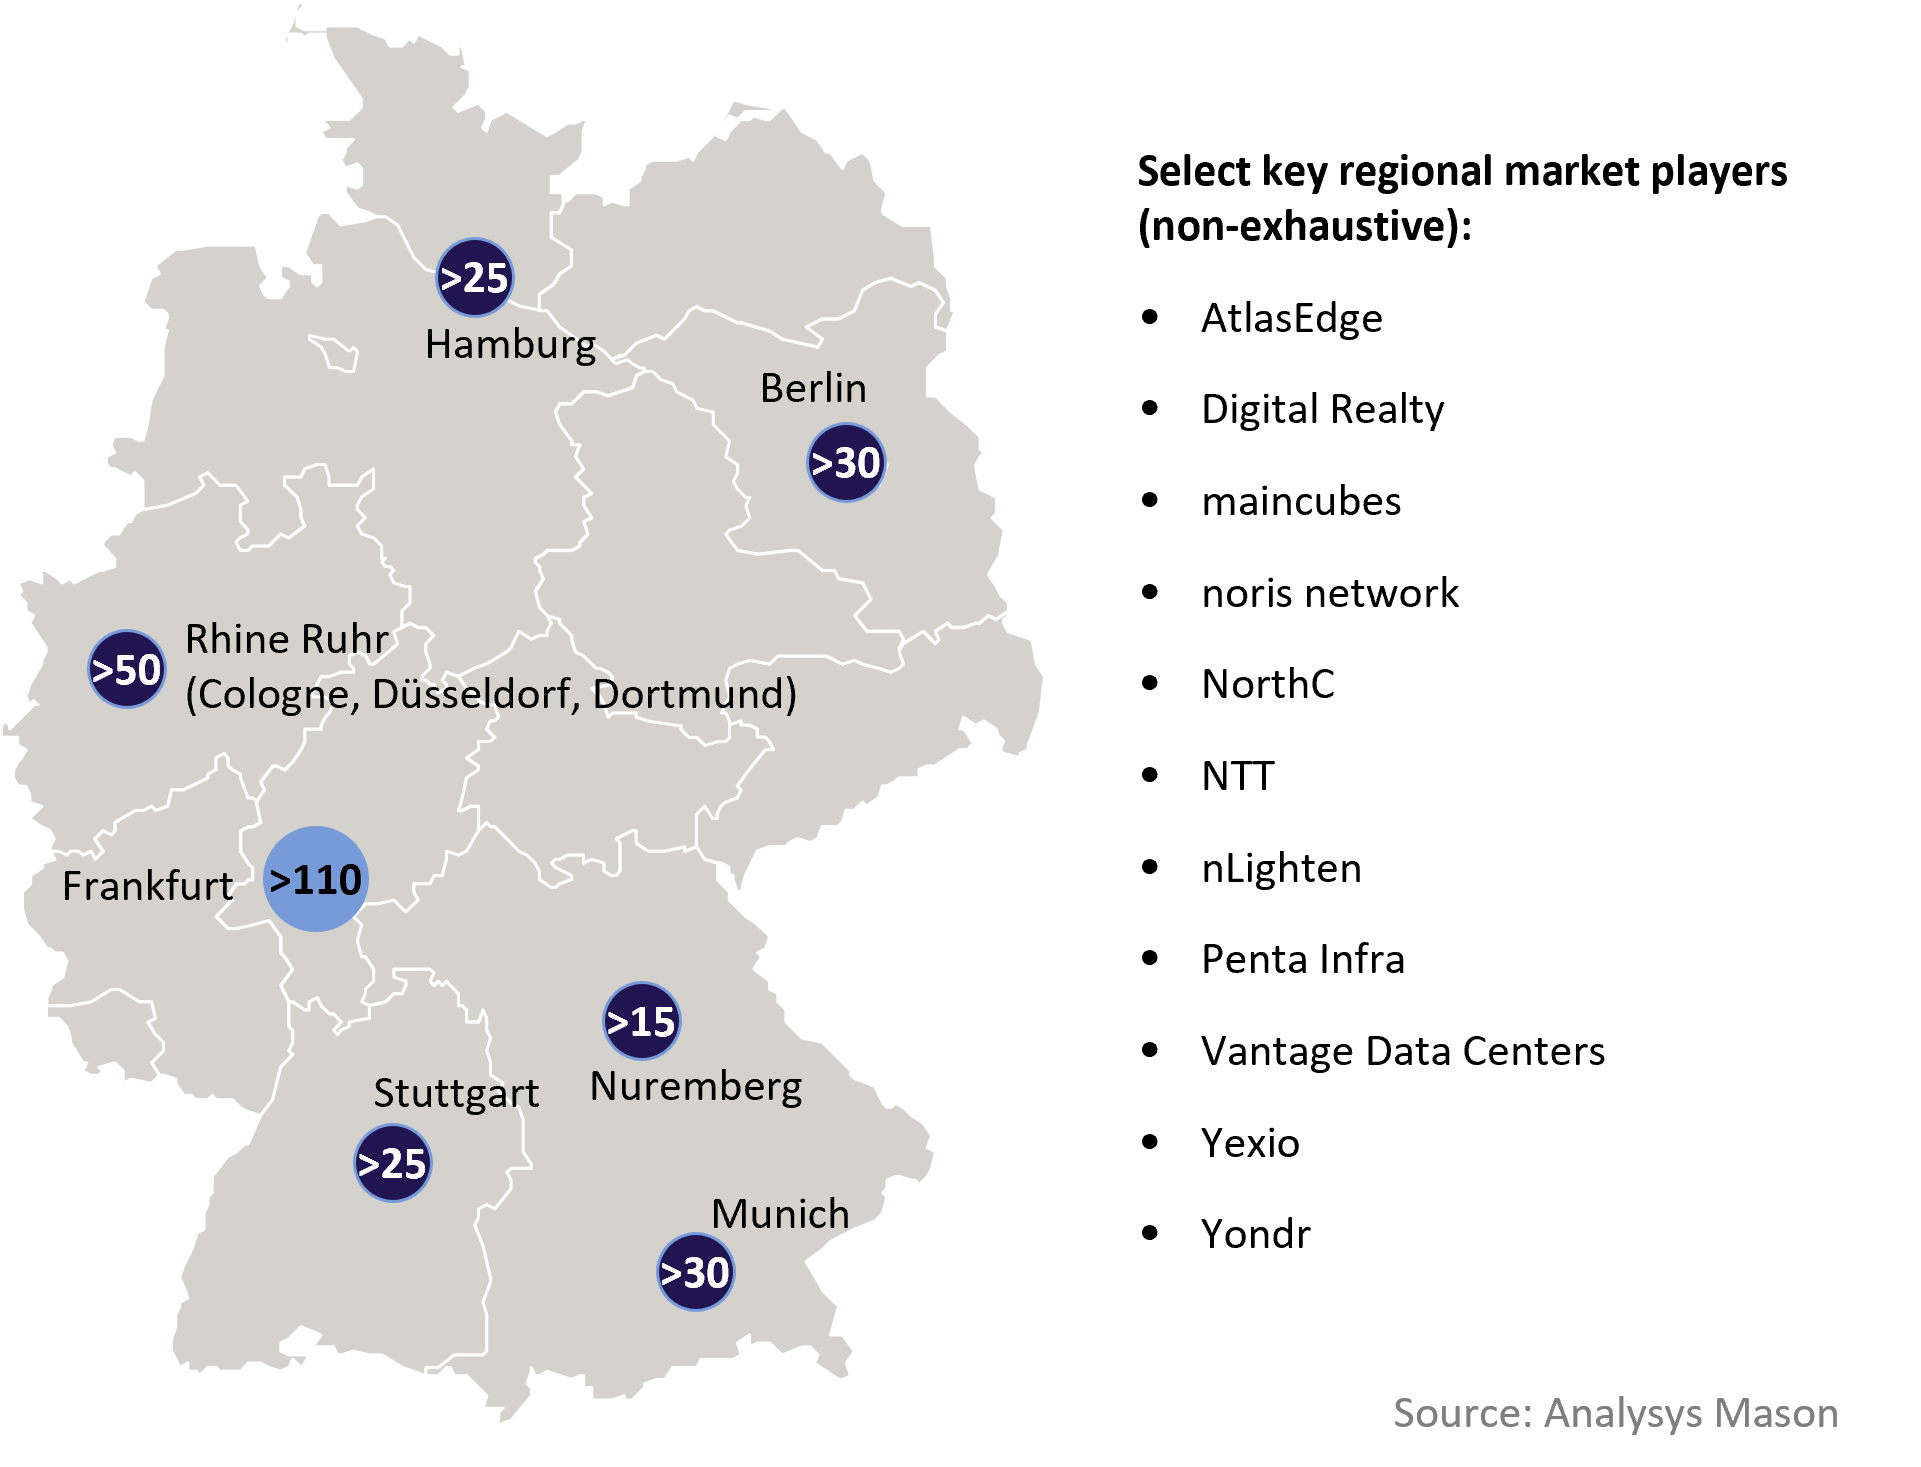
While Frankfurt remains Germany’s largest co-location market, several metropolitan hubs are experiencing growth rates that surpass those of Frankfurt. Major co-location markets have emerged across Berlin, Munich, Cologne/Düsseldorf, Hamburg, Stuttgart and Nuremberg, reflecting a broader shift towards a more geographically diversified data centre landscape (see Figure 1).
Figure 1: Number of co-location data centres in Germany, by region (live and facilities under construction), as of September 2026
Growth in Germany’s regional data centre markets is being driven primarily by enterprise demand for co-location services. Several factors are underpinning this trend:
- Proximity of data centre locations to major operating sites is especially important to German SMBs, enabling shorter driving distances for IT teams to access their servers. In addition, many enterprises continue to operate hybrid IT environments that combine cloud infrastructure with on-premises systems. Regional co-location sites facilitate more efficient and cost-effective connectivity between these environments. Proximity also enables providers to deliver critical on-site services, such as remote hands, hardware replacement and direct technical support, more effectively.
- Lower latency requirements are also supporting demand in regional markets. Applications in manufacturing, industrial automation and real-time communications benefit from reduced network latency and faster response times, which can be achieved through geographical proximity to end users. The growing adoption of AI is reinforcing this trend. While AI model training is typically concentrated in large hyperscale facilities, AI inference workloads often need to be processed closer to users and applications, driving a more distributed deployment of computing capacity across multiple regions.
- Data sovereignty and regulatory compliance represent another key demand driver. Public-sector organisations and enterprises operating in regulated industries frequently favour local or regional data-hosting solutions, which can simplify compliance with increasingly stringent data protection, security and governance requirements relative to public-cloud services.
- Finally, redundancy and resilience requirements are becoming increasingly important. The growing focus on business continuity, cyber resilience and regulatory compliance is increasing demand for geographically diverse data centre footprints. As a result, German Tier II markets are benefiting not only from local enterprise IT demand but also from secondary-site and disaster recovery deployments designed to enhance operational resilience.
National growth forecasts conceal supply–demand imbalances at city level
The dominant industries in each metropolitan area (see Figure 2) influence the nature of local demand, creating distinct customer bases and demand drivers across Germany's major data centre markets.
Figure 2: Dominant industries by metropolitan area, as of September 2026
| Metropolitan area | Dominant industries |
| Frankfurt | Financial services, software and software as a service (SaaS), digital platforms |
| Berlin | Digital economy including start-ups, software and SaaS, public sector |
| Munich | Automotive, industrials, high-tech, insurance, software and SaaS |
| Cologne/Düsseldorf | Telecoms, media, consumer goods, industrials, logistics, chemicals and pharmaceuticals, insurance |
| Hamburg | Logistics, port and maritime industries, media, aviation |
| Stuttgart | Automotive, mechanical engineering, industrial automation |
| Nuremberg | Industrials, ICT and software, public sector |
Source: Company data and Analysys Mason
We expect aggregate co-location demand in Germany to exceed available MW supply through 2030. However, this picture will not be uniform across the country and will depend largely on differences in regional economic growth, the concentration of digital and data-intensive industries in individual metropolitan areas, and the amount of existing and planned data centre capacity available in each market.
As a result, some metropolitan markets are expected to face supply shortages, where additional data centre capacity is likely to be absorbed rapidly by the market. Conversely, other markets may experience periods of excess supply, highlighting the importance for data centre investors of carefully assessing market attractiveness and phasing new capacity in line with local market conditions.
Multi-market platform strategy will determine investor returns
Investment opportunities in Germany’s fast-growing regional data centre markets are attracting increasing interest from private equity investors, infrastructure funds and pension funds. As a result, the country is witnessing the emergence of regional data centre platforms with geographically diversified footprints spanning multiple metropolitan areas (see Figure 3).
Figure 3: Platforms catering to growing regional demand for co-location in German metropolitan areas, as of September 2026
| Platform | Profile | Ownership | German metro areas | Capacity |
| AtlasEdge | Pan-European edge data centre platform that designs, builds and operates highly connected co-location facilities across major European regional markets (joint venture) | Joint venture between Liberty Global (majority) and DigitalBridge (minority) | Cologne/Düsseldorf, Berlin, Stuttgart, Hamburg | 36.2MW (live) 4.4MW (planned) |
| nLighten | Pan-European edge data centre platform that operates a distributed network of regional, carrier-neutral facilities across Europe | Majority private equity-owned: I Squared Capital |
Frankfurt, Berlin, Munich, Cologne/ Düsseldorf, Hamburg, Stuttgart, Nuremberg, Hannover, Leipzig |
18MW (live) |
| Penta Infra | European edge data centre operator, focused on providing carrier-neutral co-location and connectivity services through a network of regional, highly connected facilities in key European metropolitan markets | Majority private equity-owned: Photon Capital (~51%) and PGGM1 (~49%) | Cologne/Düsseldorf, Berlin, Munich (planned), Hamburg, Leipzig | 8.1MW (live) 20MW (planned) |
| NorthC Datacenters | Regional data centre platform in Northwest Europe, providing sustainable co-location and connectivity services through a network of carrier-neutral facilities across the Netherlands, Germany and Switzerland | Antin Infrastructure Partners (acquired from DWS and minority shareholders in 2026) | Frankfurt, Berlin, Munich, Cologne/ Düsseldorf, Hamburg, Nuremberg |
6.5MW (live) 33.4MW (planned) |
| Yexio | Data centre platform with decentralised sustainable edge facilities that support sovereign cloud, AI and Industry 4.0 workloads close to end users. First data centre launched in 2025, with an additional 15 data centres planned across Germany | Joint venture between HOCHTIEF PPP Solutions and Palladio Partners | Munich (planned), Cologne/Düsseldorf, Bremen (planned), Hannover (planned) | 2MW (live) 14MW (planned) |
Source: Company websites and Analysys Mason
The emergence of additional platforms focused on regional markets is expected over the coming years. This growth is likely to be driven both by the geographical expansion of regional data centre operators into additional metropolitan markets and by buy-and-build strategies pursued by investors seeking to establish larger, multi-site platforms.
City-by-city diligence is essential to convert growth into returns
For investors in German data centres, success will also depend on identifying the metropolitan areas and platform strategies best placed to benefit from growing regional supply–demand imbalances. Analysys Mason helps investors look beyond headline growth rates to assess local market fundamentals city by city. The rise of regional platform operators such as AtlasEdge, nLighten, Penta Infra, NorthC and Yexio highlights the attractiveness of regional co-location markets and the potential for buy-and-build strategies.
We support investors throughout the investment lifecycle by:
- identifying the most attractive regional markets through detailed analysis of local demand drivers, industry concentration, digitalisation trends and enterprise co-location requirements
- forecasting supply–demand gaps at metropolitan level to identify markets where future shortages may create pricing power and attractive returns
- assessing platform strategies and evaluating whether operators have the right geographical footprint to capture regional demand
- supporting commercial due diligence through market sizing, demand forecasting, competitive assessment and customer validation
- evaluating buy-and-build opportunities by identifying acquisition targets, synergy potential and expansion priorities
- testing investment theses around AI, sovereign cloud, enterprise co-location and edge computing to distinguish structural growth opportunities from short-term market hype.
Speak to our team to learn how the issues raised in this article could influence your investment decisions and growth plans.
1 Investing for the Dutch pension fund.
Germany’s regional data centre opportunity: geographical selection and platform strategy will determine investor returns
Authors
Mirko René Gramatke
Partner, expert in transaction services
Daniel Ponte Fernández
Principal, expert in transaction services
Mark Maczat
Principal, expert in transaction support for digital infrastructure, software and ICT services
Marcel Philippe Quasigroch
ManagerRelated items
Article
A guide to today’s data centre ecosystem
Article
From ambition to action: how EU-backed gigafactories could redefine AI investment
Article
USD310 billion and growing: the data-centre supply chain is a major growth opportunity for creative investors